
PMI Playbook — Buys & Sells
The ISM Report On Business is one of the highest-signal macro releases most people never read. What this month’s numbers say, which sectors that favours, and where to read the full report yourself — free.
The buys and sells
From the September report, released 1 October — manufacturing 54.5, a ninth straight month of expansion but now with only 12 of 18 industries growing, down from 15. The tilts below come from the industry rankings inside the report, not from the headline. Research starters, not advice.
- Electrical equipment & grid #1 of 12 growing, jobs #1
- Semiconductors computer/elec, orders #3
- Building materials nonmetallic minerals, orders #1
- Steel primary metals #3, jobs #2
- Long-duration bonds prices 77.9, 10Y 5.29%
- Rate-sensitive housing wood orders ▾, permits trend ▾
- Transports DJ Transports −9.0% in Sept
- Chemicals #12 of 12, jobs ▾
- Packaged food & staples food & bev jobs ▾
The two changes from September’s list: Financials come off the sell side — the curve stopped flattening and Finance & Insurance returned to growth in the services survey, which were the two reasons it was there — and broad Materials narrows to steel, because the metals-and-mining basket fell 8.8% while it was on the buy list and the ISM now ranks primary metals below two other industries.
What the read means
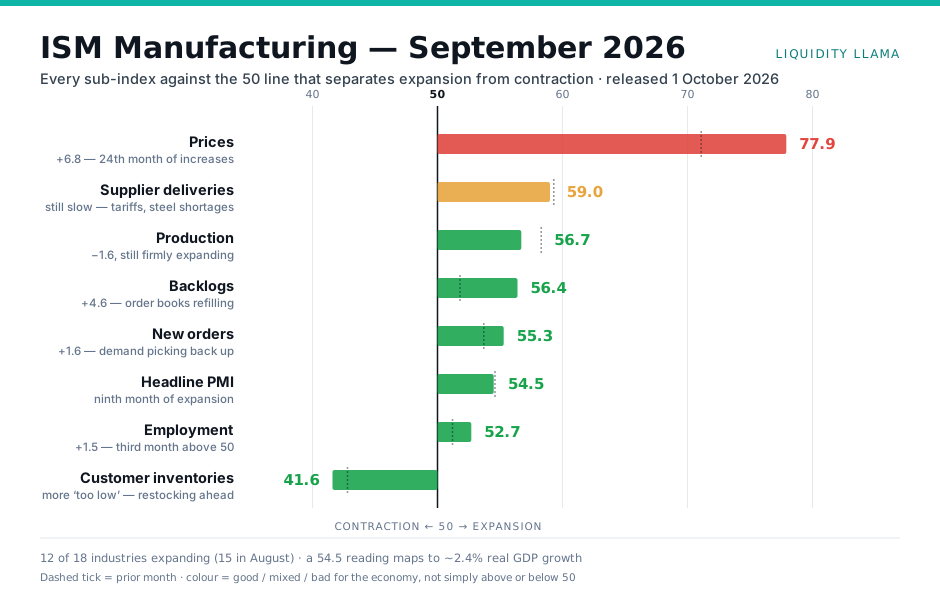
Manufacturing at 54.5 is a tenth of a point below August and still the ninth consecutive month of expansion. ISM’s own translation is unchanged: a reading this high historically corresponds to real GDP growing at about 2.4% annualised. On the headline alone, nothing happened. Underneath it, three things moved a lot.
- Prices paid jumped 6.8 points to 77.9. A 24th straight month of rising input costs, and the largest monthly move in any line of the report. TD Economics called it “the clearest concern” in the release, pinning it on steel and aluminium tariffs and petroleum costs. Services prices rose too, to 74.0. This is the line that matters most for markets, because it lands in the middle of a Fed hiking cycle.
- The order book refilled. New orders rose 1.6 to 55.3 and backlogs jumped 4.6 to 56.4, reversing most of August’s fall. Production slipped to 56.7, so firms are taking on work faster than they are clearing it — the opposite of August, and the better way round for the next few months of output.
- Breadth narrowed. Twelve of 18 industries grew, down from 15. Two contracted (Printing, and Textile Mills) and four reported no change. Growth is concentrating in metals, electrical equipment and electronics — the industries tied to data-centre and grid build-out.
The purchasing managers’ own words explain the split. A machinery maker: “Orders have doubled yet again, and delivery times have also doubled, in the semiconductor, electronics and government sectors, with remaining sectors flat to down.” A transportation-equipment respondent: “Buying continues to get pushed out indefinitely as customers don’t want to spend on capital expenditures until there is more certainty of costs and demand.” And from chemicals, the industry that just squeaked back onto the growth list: “these factors do not signal sustained recovery.” According to ISM, 34% of negative comments mentioned tariffs and 30% mentioned the Iran war.
The verdict
- New orders 55.3 (+1.6) and backlogs 56.4 (+4.6). The order book is refilling faster than production is drawing it down, which supports output into year-end.
- Factory employment 52.7 (+1.5), a third consecutive month above 50 after 33 below. Manufacturing payrolls added 9k in September, so the hard data agrees here.
- Customer inventories 41.6, a 24th month “too low” and lower than August. Thin customer stock forces restocking regardless of end demand.
- Services new orders 59.8 and services employment back to 50.1. The larger half of the economy is still growing.
- Electrical Equipment ranks #1 of 12 on growth, #2 on new orders and #1 on employment. When one industry tops all three lists, the signal is about as clean as this report gives.
- Prices 77.9 (+6.8), services prices 74.0, and one-year consumer inflation expectations at 4.6% (University of Michigan). Inflation pressure is re-accelerating in a hiking cycle.
- Payrolls +29k, with −60k of revisions. July is now negative. Unemployment 4.2%. The labour market is weaker than any of the surveys show.
- The 10-year rose 54bp in September to 5.29%. Long bonds (TLT) fell 6.6% from the August close. Every rate-sensitive sector on the sell list fell with them.
- Only 12 of 18 industries growing, from 15. Machinery fell to #10 of 12 and Transportation Equipment to #9, so the expansion is narrowing to the AI and grid supply chain.
- DJ Transports −9.0% in September, to 19,382. Freight equities are the model’s heaviest input, and they fell hard while the S&P 500 was roughly flat.
- September CPI, 14 October. After a 77.9 prices index, a hot CPI makes a second hike likely. A soft one is the single biggest risk to the short side of this list.
- The Fed, 27–28 October. It hiked to 3.75–4.00% on 16 September. After the payrolls miss, futures priced the odds of an October hike at only about 14%. The prices data argues the other way.
- DJ Transports against 19,382. It is up 2.1% in October so far. An October close above its September close flips the heaviest row of the regime model.
- October ISM, 2 November. Whether prices stay above 75, and whether Electrical Equipment and Computer & Electronic Products stay near the top of the new-orders list.
- October payrolls, 6 November. A second sub-50k print with more downward revisions would turn the Labour row of the model bearish.
Names the framework points at
Each of these comes from a specific number in the report, not from how a chart looks. They are screens to research, not positions. No entry prices, targets, stops or position sizes — the level you pay and how much you risk are your decisions, and the point of this list is the reasoning.
| Idea | Which number drives it | What kills the thesis |
|---|---|---|
| Grid & electrical equipment ETN · PWR · HUBB · GRID |
Electrical Equipment ranks #1 of 12 growing industries, #2 on new orders and #1 on employment — the only industry near the top of all three lists. | Electrical Equipment dropping out of the top five on new orders in the 2 November report, or a hyperscaler cutting capex guidance. |
| Semiconductors & equipment SMH · NVDA · AMAT |
Computer & Electronic Products ranks #3 on new orders but only #5 on growth: orders leading activity, which is the improving pattern. A machinery respondent reports orders from semiconductor customers “doubled yet again”. | Computer & Electronic falling off the new-orders growth list. SMH is already up 13.9% since the August close, so the bar for disappointment is low. |
| Aggregates & building materials VMC · MLM |
Nonmetallic Mineral Products ranks #1 on new orders and #2 on growth. That is concrete, cement and aggregates, which here is non-residential and infrastructure demand rather than housing. | Nonmetallic Minerals leaving the top five on new orders, or Construction’s contraction in the services survey deepening into non-residential work. |
| Steel with pricing power NUE · STLD |
Primary Metals ranks #3 on growth and #2 on employment, and prices paid hit 77.9 on tariffed steel. A machinery maker: “domestic steel capacity has been stretched”. | Prices paid falling back below 71, or Primary Metals slipping further on new orders (it is #6 there already, below its #3 growth rank — a fading pattern). |
| Industrial distributors FAST · GWW |
Customer inventories 41.6, more “too low” than August’s 42.8 and a 24th month below 50. Distributors are the first read on restocking. | Customer inventories climbing back above 48: restocking done. |
| Long-duration Treasuries TLT · ZROZ |
Prices 77.9, services prices 74.0 and one-year inflation expectations at 4.6%, with the 10-year at 5.29% and still above its 12-month mean of 4.41%. A weak payrolls print did not bring yields down. | A soft September CPI on 14 October followed by the Fed holding on 28 October. That combination would rally long bonds fast. |
| Homebuilders & housing XHB · DHI · LEN |
Permits’ 6-month average of 1,401k sits under the 12-month average of 1,425k. Wood Products is on the falling-new-orders list. Construction contracted in the services survey: “Half of buyers walking through the door cannot qualify.” | The 6-month permits average crossing back above the 12-month, or the 10-year falling back under 4.41%. |
| Transports IYT · ODFL · JBHT |
DJ Transports −9.0% in September. Transportation Equipment fell to #9 of 12, with a respondent describing purchases “pushed out indefinitely”. Diesel costs appear in comments across agriculture and food. | DJ Transports closing October above 19,382, its September close. It was 2.1% above that on 5 October, so this one is close to being wrong. |
| Cost-squeezed processors DOW · LYB · XLP |
Chemical Products is #12 of 12 on growth and Chemicals and Food, Beverage & Tobacco are both on the falling-employment list, while prices paid hit 77.9. A food respondent: beef costs high “with no relief in sight”. | Prices paid dropping back toward 71, or Chemical Products moving up the growth list for a second month. |
How last month’s names did
From the August close (31 August) to 5 October. The S&P 500 (SPY) rose 1.0% over the same period. Short and avoid ideas are on the right side when they fall.
| Name | Side | Move | Verdict |
|---|---|---|---|
| CAT · ETN · PH | Long | +6.4% · +7.6% · −0.4% | ETN stays (grid). CAT and PH come off: Machinery fell to #10 of 12. |
| FAST · GWW | Long | +2.8% · −1.7% | Flat. Stays — customer inventories fell further. |
| NUE · STLD · FCX · XME | Long | +0.7% · +3.6% · −4.1% · −8.8% | Wrong on the basket. Narrowed to NUE and STLD; FCX and XME come off. |
| ETN · PWR · VRT | Long | +7.6% · +12.6% · −2.0% | Right. ETN and PWR stay; VRT swaps for HUBB. |
| XLF · JPM | Short | −6.6% · −6.6% | Right on price, but the curve reason faded. Comes off. |
| TLT · ZROZ | Short | −6.6% · −10.0% | Right. Stays. |
| XLU · XLP | Short | −5.4% · −4.6% | Right. XLP stays (food jobs falling); XLU comes off — Utilities grew in the services survey. |
| XHB · DHI · VNQ | Short | −6.3% · −7.8% · −7.6% | Right. XHB and DHI stay; VNQ swaps for LEN. |
The honest summary: every short worked, and the long list split. The two longs tied to the AI build-out (semiconductors and grid equipment) beat the market by a wide margin. The two tied to the broad goods cycle (materials and machinery) lost money. In other words, the September list made money on rates and on AI capex, not on the ISM cycle it was supposed to be reading. The semiconductor tilt we called the weakest of the four did best, with SMH up 13.9%.
Read it yourself. It’s free
You don’t need a terminal or a subscription for any of this. The ISM Report On Business is published free, in full, and most people never look at it. Two places to find it:
ismworld.org. The month is the last part of the address, so you can jump to any month by changing one word:
ismworld.org/…/ism-pmi-reports/pmi/september/
This is the one to read. It carries all 18 industries ranked in order and the verbatim comments from the purchasing managers themselves. Those are the two things that turn a headline number into an actual view, and the two things every news summary throws away.
PR Newswire publishes it free the moment it’s released: first business day of the month for manufacturing, third for services.
Identical headline and sub-index figures, plain text, no sign-up. If you only want the numbers, this is quicker.
What to do with it. Read the manager comments first. Sixty seconds of people describing their own order books tells you more than the headline number does. This month, they described a two-speed economy: machinery orders doubling for semiconductor customers while transport-equipment customers pushed purchases out “indefinitely”. Then compare each industry’s rank on new orders with its rank on overall growth. An industry ranked higher on orders than on growth is improving; one ranked lower is fading.
If you want a second opinion on the interpretation, TD Economics and PNC both publish free same-day notes and will flag anything odd in the seasonal adjustment before you build a view on it.
Sources
- ISM — September 2026 Manufacturing PMI Report On Business
- PR Newswire — Manufacturing PMI at 54.5%, September 2026 (sub-indexes, industry rankings, respondent comments)
- PR Newswire — Services PMI at 54.9%, September 2026
- TD Economics — U.S. ISM Manufacturing Index
- PNC Economics Research — ISM Manufacturing Survey, 1 October 2026
- BLS — Employment Situation, September 2026
- FRED — 10-year and 2-year Treasury yields
Not investment advice. The tilts and names are framework-generated research starters, not recommendations to buy or sell anything. Market data as at the 5 October 2026 close. Sources: September 2026 ISM Manufacturing and Services Reports On Business via PR Newswire; TD Economics; PNC Economics Research; BLS.