
PMI Playbook — Buys & Sells
The ISM Report On Business is one of the highest-signal macro releases most people never read. What this month’s numbers say, which sectors that favours, and where to read the full report yourself — free.
The buys and sells
From the August report, released 1 September — manufacturing 54.6, down a point but an eighth straight month of expansion, with 15 of 18 industries still growing. The tilts below come from the industry rankings inside the report, not from the headline. Research starters, not advice.
- Materials primary metals #1 of 15
- Industrials elec. equipment #2 of 15
- Semiconductors computer/elec, orders #6
- Data-center / power capex theme
- Chemicals contracting, orders & jobs ▾
- Financials curve flat, Fin. & Ins. contracting
- Long-duration bonds 10Y at 5.17%
- Rate-sensitive housing wood products contracting
- Construction contracting in Aug services
- Defensives food & bev orders ▾
The semiconductors tilt is the weakest of the four. Computer and electronic products ranks only #12 of the 15 growing industries, so that call rests mainly on AI capex rather than on the ISM data.
What the read means
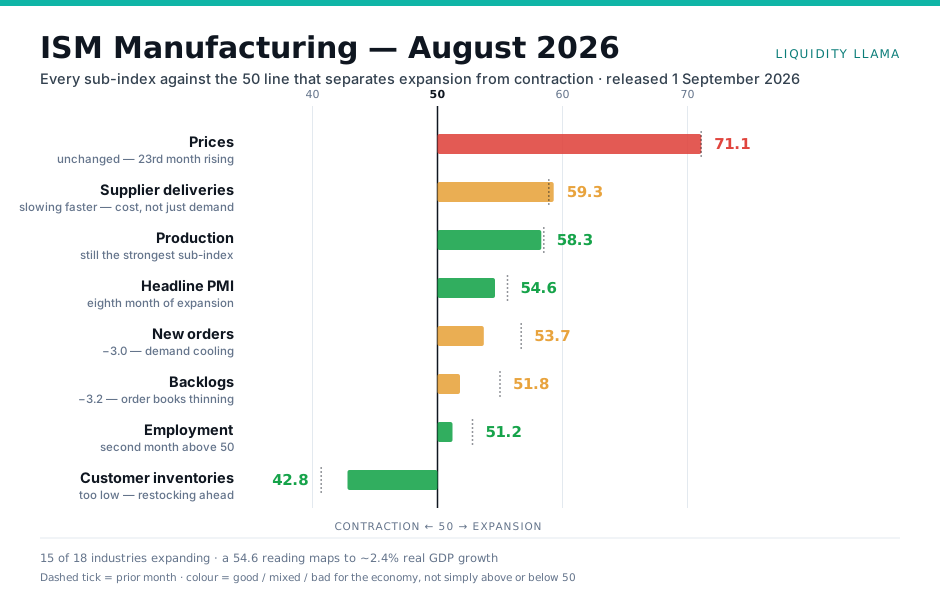
Manufacturing at 54.6 is down a point from July but still the eighth consecutive month of expansion. ISM’s own translation: a 54.6 reading historically corresponds to real GDP growing at about 2.4% annualised, against 2.8% last month. The cycle is cooling, not turning.
Three things in the release matter more than the headline:
- New orders fell 3.0 points to 53.7. This is the forward-looking line and it was one of the biggest falls in the report, alongside backlogs and imports, which each fell 3.2. Still expanding, but the order book is filling more slowly than it was.
- Backlogs fell 3.2 to 51.8. Read alongside production holding at 58.3, that says firms are clearing existing work faster than new work arrives. That is the opposite of July, when backlogs jumped and new orders led.
- Factory employment held above 50 at 51.2, down from 52.8. A second month of expansion after 33 below is the one genuinely encouraging line, and it is losing momentum rather than building it.
The awkward line is prices at 71.1, unchanged from July and a 23rd straight month of increases. Supplier deliveries slowed further to 59.3. Costs are not easing and have not eased for nearly two years. Combined with hot input prices, that shapes the tilt toward cyclicals that can pass those costs on rather than cyclicals generally.
The verdict
- Services accelerating hard. 55.4 from 54.1, with new orders at 60.9. The larger half of the economy sped up while manufacturing cooled.
- Production held at 58.3, the strongest of the activity sub-indexes and barely changed on the month. Only supplier deliveries (59.3) and prices (71.1) read higher, and those describe supply strain and cost.
- Customer inventories at 42.8. Still far too low. Stock levels this thin force restocking: demand you can see coming rather than demand you have to forecast.
- Breadth held. 15 of 18 industries still expanding, led by primary metals. The slowdown is in the pace, not the breadth.
- The curve is flattening into this. 10Y−2Y at 0.36pp (25 September), down from 0.50 in late August, with the 10-year at 5.17%. A cooling goods cycle financed at rising long rates is a materially worse trade than one financed cheaply.
- Prices unchanged at 71.1, a 23rd straight month of increases, and supplier deliveries slowed further to 59.3. Slower deliveries flatter the headline PMI while describing a cost problem.
- Wood Products and Chemical Products are both contracting, and both sit on the declining-new-orders list. Chemicals is shedding employment too, so it alone fails all three tests; Wood Products fails two. Housing’s input has led every meaningful cycle turn in forty years, and it is not confirming this one.
- The level holds but momentum is fading. New orders −3.0, backlogs −3.2, employment −1.6. Most forward-looking lines fell while the headline stayed above 50. New export orders were the exception, rising to 53.2.
- The Fed. It hiked a quarter point on 16 September, to 3.75–4.00%, as futures expected. The September dot plot implies one more hike this year (a median of about 4.1% at the end of 2026), and prediction markets price a December hike at about two-thirds. Services prices at 72.6, up from 70.3 and accelerating, are the strongest support for that risk. A second hike would hurt cyclicals more than anything else in this report.
- Whether the curve stops flattening. The regime model scores it −1 while it narrows or sits below 0.25pp, and −2 only if it inverts. At 0.36pp it is 11 basis points above the 0.25 line.
- Services employment at 47.8, a second month contracting, even as services activity accelerated. The +162k August payrolls eased the worry, but one print does not settle it.
- Prices paid rolling over. Falling input costs turn a demand recovery into a margin recovery, which is a different and better trade.
- Building permits, and Wood Products with them. If both turn up, the clearest hole in the cyclical case closes.
Names the framework points at
Each of these comes from a specific number in the sub-indexes above, not from how a chart looks. They are screens to research, not positions. No entry prices, because the level you pay is your decision and the point of this list is the reasoning.
| Idea | Which number drives it | What kills the thesis |
|---|---|---|
| Machinery & electrical equipment CAT · ETN · PH |
Production held at 58.3, and Electrical Equipment ranks #2 of the 15 growing industries. These convert a backlog into revenue first. | Already weakening: backlogs fell 3.2 to 51.8. Under 50 and the order book is emptying faster than it refills. |
| Industrial distributors FAST · GWW |
Customer inventories 42.8, still far too low. Distributors are the most direct read on restocking because they sell the pick-and-shovel consumables first. | Customer inventories climbing back above 48; restocking already done. |
| Materials into restocking NUE · STLD · FCX · XME |
Primary Metals ranks #1 of 15 on growth and #3 on new orders, with customer inventories at 42.8. Volume recovery reaches raw inputs before finished goods. XME (metals and mining) stands in for the broad materials fund, because XLB is about a third chemicals, which the sell list underweights. | China demand disappointing, or the dollar strengthening hard. |
| Banks into a flattening curve XLF · JPM |
A buy on a steep curve in August. 10Y−2Y has gone from 0.50pp in late August to 0.36pp with the short end rising faster. Banks fund short and lend long; that spread is the margin, and it is compressing. Finance & Insurance was also contracting in the August services survey. | The curve re-steepening, or loan volume growing fast enough to offset a thinner spread. |
| Data-centre power capex ETN · PWR · VRT |
The one theme where the ISM cycle and the AI capex cycle point the same way. Grid connections are the bottleneck. | A hyperscaler cutting capex guidance. This is the theme’s single point of failure. |
| Long-duration Treasuries TLT · ZROZ |
A 54.6 PMI implying 2.4% real GDP, with prices paid stuck at 71.1, is not a backdrop that rallies 30-year bonds. | A bad payrolls miss. A growth scare bids long bonds hard and fast. |
| Bond-proxy defensives XLU · XLP |
Food, Beverage & Tobacco is the weakest of the 15 growing industries and sits on both the falling-new-orders and falling-employment lists. The yield also competes with a 5.17% ten-year. | If growth cracks properly, defensives are the right hedge if deceleration becomes contraction. |
| Rate-sensitive housing XHB · DHI · VNQ |
Wood Products is contracting outright and on the falling-new-orders list. Construction was contracting in the August services survey. Permits trending down, mortgage rates following a 5.17% long end higher. | Permits turning up, or a genuine dovish shift at the long end. |
Read it yourself. It’s free
You don’t need a terminal or a subscription for any of this. The ISM Report On Business is published free, in full, and most people never look at it. Two places to find it:
ismworld.org. The month is the last part of the address, so you can jump to any month by changing one word:
ismworld.org/…/ism-pmi-reports/pmi/august/
This is the one to read. It carries all 18 industries ranked in order and the verbatim comments from the purchasing managers themselves. Those are the two things that turn a headline number into an actual view, and the two things every news summary throws away.
PR Newswire publishes it free the moment it’s released: first business day of the month for manufacturing, third for services.
Identical headline and sub-index figures, plain text, no sign-up. If you only want the numbers, this is quicker.
What to do with it. Read the manager comments first. Sixty seconds of people describing their own order books tells you more than the headline number does. You’ll see tariffs, shortages and hiring freezes in plain language weeks before they show up in official data. Then check whether the sub-indexes agree with each other: production and new orders rising together is a real expansion, production rising while new orders fall is a company working through a backlog it hasn’t replaced.
If you want a second opinion on the interpretation, TD Economics and PNC both publish free same-day notes and will flag anything odd in the seasonal adjustment before you build a view on it.
Sources
- ISM — August 2026 Manufacturing PMI Report On Business (headline, sub-indexes, industry rankings)
- ISM — August 2026 Services PMI Report On Business
- PR Newswire — Services PMI at 55.4%, August 2026 ISM Services PMI Report (industry rankings, including Construction and Finance & Insurance)
- Federal Reserve H.15 — Selected Interest Rates (10-year yield, curve)
Not investment advice. The tilts are framework-generated research starters. Sources: August 2026 ISM Manufacturing and Services Reports On Business via PR Newswire; TD Economics; PNC Economics Research.